
Blue Raider Adventure Park accounting refers to an accounting cycle case associated online with ACTG 2110, Principles of Accounting I, at Middle Tennessee State University (MTSU). Publicly indexed course material presents Blue Raider Adventure Park as a business scenario used to practice recording transactions and carrying accounting information through the financial accounting cycle.
The material should not be confused with a publicly documented commercial attraction called Blue Raider Adventure Park. The available evidence points instead to an educational accounting exercise. An indexed version describes an MTSU student named Matt Lapinski developing an adventure park on his grandfather’s land, with activities such as canoeing, spelunking tours, obstacle courses, and ziplining.
What Is Blue Raider Adventure Park Accounting?
The phrase blue raider adventure park accounting is most closely connected to an MTSU accounting assignment described as an Accounting Cycle Packet Serial Problem Covering Chapters 2 through 4. The exercise places students inside a small business scenario and requires them to apply accounting principles rather than simply answer isolated multiple choice questions.
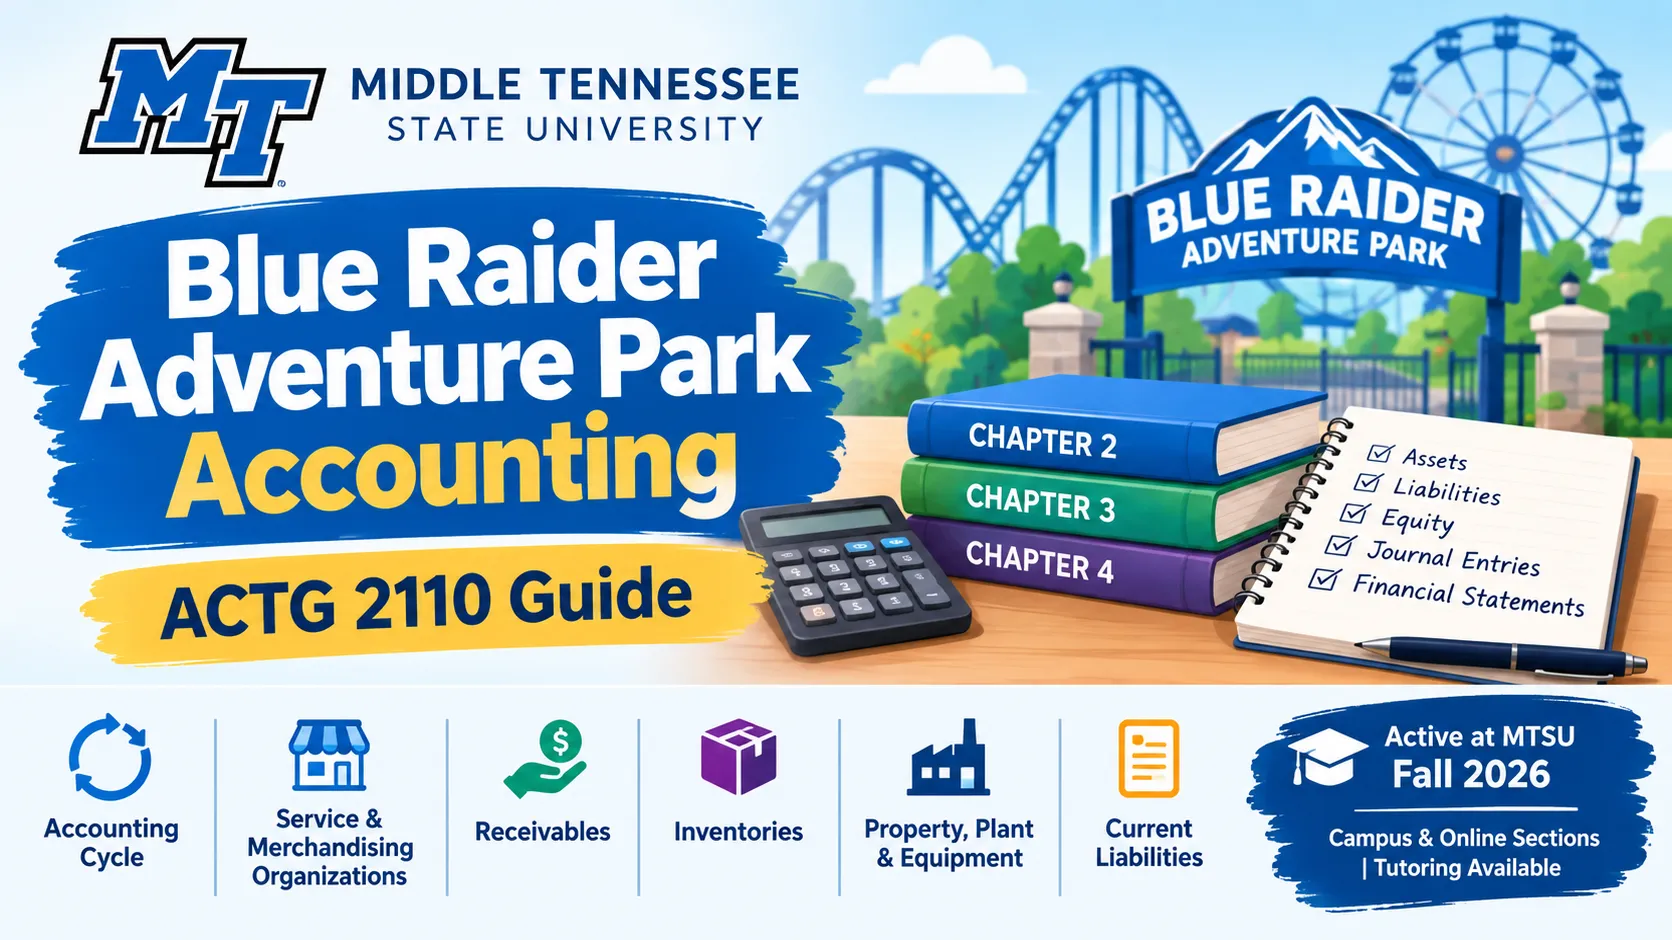
That connection makes sense academically. MTSU describes ACTG 2110 as a three credit undergraduate course covering financial accounting for proprietorships and partnerships, with particular emphasis on the accounting cycle for service and merchandising organizations. The official course description also includes receivables, inventories, property, plant and equipment, and current liabilities.
ACTG 2110 remains an active MTSU course in Fall 2026, with both campus and online sections appearing in the university’s current schedule. MTSU also lists tutoring for ACTG 2110 among its Fall 2026 accounting support services.
Why the Assignment Uses the Name “Blue Raider”
“Blue Raiders” is the official nickname associated with Middle Tennessee State University. MTSU Athletics identifies the university’s nickname as the Blue Raiders and its mascot as Lightning. The nickname has been used by Middle Tennessee athletic teams since the 1930s.
The name Blue Raider Adventure Park therefore fits naturally with an MTSU classroom case. However, the university sources reviewed do not establish Blue Raider Adventure Park itself as an MTSU operated attraction or an actual commercial business.
This distinction matters because searches for the keyword can easily make the assignment appear to be information about a real amusement or adventure park.
What the Blue Raider Adventure Park Case Is Designed to Teach
The central skill is understanding how one business event moves through an entire accounting system.
A transaction is not finished once its debit and credit are written in a journal. It may affect the general ledger, trial balance, adjusting entries, financial statements, and eventually the closing process.
OpenStax describes the accounting cycle as a continuous process that begins with identifying and analyzing transactions. Transactions are journalized, posted to the ledger, summarized in a trial balance, adjusted when necessary, and eventually used to prepare financial statements.
For a serial problem such as Blue Raider Adventure Park, this is particularly important. A mistake made when the original transaction is analyzed can continue into every later stage.
Blue Raider Adventure Park Accounting Cycle Explained
The precise transactions and amounts should always come from the version of the assignment issued by the instructor. Public search results do not provide a reliable complete current packet, so specific figures should not be assumed from unofficial answer pages.
The accounting method itself, however, follows established financial accounting principles.
1. Identify and Analyze Each Transaction
The first question is not “Which side is the debit?” It is:
What actually happened to the business?
Students should determine:
- Which accounts changed
- Whether each account increased or decreased
- What type of account each one is
- Which amount belongs on the debit side
- Which amount belongs on the credit side
The fundamental accounting equation must remain balanced:
Assets = Liabilities + Equity
For an adventure park scenario, transactions could involve assets such as cash, equipment, or supplies and liabilities such as accounts payable. Revenue and expenses ultimately affect equity.
Those are examples of how such a business can be analyzed, not a claim that every one of these accounts appears in every Blue Raider Adventure Park packet.
2. Record the General Journal Entries
After analyzing the transaction, it is recorded chronologically in the journal.
OpenStax identifies the journal as the first formal location where accounting information is entered. The journal entry records the accounts involved, the debits and credits, the date, and normally a brief explanation.
Some common transaction patterns useful when working through a service business case are:
| Business event | Typical debit | Typical credit |
|---|---|---|
| Owner contributes cash | Cash | Owner’s Capital or applicable equity account |
| Equipment purchased for cash | Equipment | Cash |
| Supplies purchased on account | Supplies | Accounts Payable |
| Cash received for services already provided | Cash | Service Revenue |
| Services performed on account | Accounts Receivable | Service Revenue |
| Customer pays an outstanding account | Cash | Accounts Receivable |
| Operating expense paid immediately | Appropriate Expense | Cash |
| Cash collected before a service is provided | Cash | Unearned Revenue |
These are general accounting patterns. Students should use the exact account titles and business structure provided in their own assignment.
Posting Entries to the General Ledger
Journalizing tells you when a transaction happened. The general ledger groups transactions according to account.
Every journal entry must therefore be posted to the appropriate ledger accounts. If Cash is affected by ten transactions, all ten eventually become part of the Cash account’s running balance.
OpenStax places posting as the third stage of the accounting cycle, immediately after journalizing. Account balances are then calculated before preparing the unadjusted trial balance.
This is one of the places where serial accounting assignments often go wrong. A perfectly correct journal entry can still produce an incorrect trial balance if it is posted to the wrong account or transferred with the wrong amount.
Preparing the Unadjusted Trial Balance
Once the ordinary transactions have been journalized and posted, account balances are transferred to an unadjusted trial balance.
The trial balance lists the general ledger accounts with nonzero balances and separates debit balances from credit balances. Total debits should equal total credits.
A useful checkpoint is:
Total Debits = Total Credits
If they do not match, students should trace the problem backward through the ledger and journal.
Equal totals, however, do not prove that every transaction is correct. OpenStax specifically notes that a trial balance can be mathematically balanced even when an accounting error remains. For example, the wrong account could have been debited and another account correctly credited for the same amount.
Adjusting Entries Are Usually the Hardest Part
Adjusting entries recognize economic activity that has occurred but is not yet correctly reflected in the accounts at the end of an accounting period.
OpenStax explains that adjustments are needed because some events do not create an immediate document or ordinary transaction entry. Supplies may be consumed over time, previously unearned revenue may become earned, expenses may accrue before payment, or long term assets may require depreciation.
Depending on the data supplied in a Blue Raider Adventure Park packet, an adjustment could potentially involve concepts such as:
Supplies Used
If supplies were originally recorded as an asset but some have now been consumed:
Debit: Supplies Expense
Credit: Supplies
The adjustment recognizes the amount actually used during the period.
Prepaid Costs That Have Expired
A business may pay in advance for insurance or another service.
As part of that benefit expires:
Debit: Appropriate Expense
Credit: Prepaid Asset
Only the portion relating to the current period becomes an expense.
Depreciation
Long term equipment is normally not treated as if its entire usefulness disappears on the purchase date.
A basic depreciation adjustment uses:
Debit: Depreciation Expense
Credit: Accumulated Depreciation
The actual depreciation amount must come from the assignment’s cost, useful life, method, dates, and any other instructions.
Accrued Expenses
An expense may already have been incurred even though cash has not yet been paid.
A typical form is:
Debit: Expense
Credit: Payable
Unearned Revenue Becoming Earned
If a customer paid before the business performed the service, the original receipt may have created a liability.
Once the required service is performed:
Debit: Unearned Revenue
Credit: Service Revenue
The key idea is that adjustments are based on what has been earned, incurred, used, or expired, not simply on whether cash has moved.
Preparing the Adjusted Trial Balance
After adjusting entries are journalized and posted, the ledger contains updated balances.
Those balances form the adjusted trial balance. OpenStax defines it as a list of general ledger accounts with nonzero balances after adjustments have been included. It is also the primary starting point for preparing the financial statements.
Students should check three things before moving forward:
- All required adjustments have been posted.
- Every account carries its final corrected balance.
- Total adjusted debits equal total adjusted credits.
Moving to the financial statements before these checks can carry an earlier error directly into net income and the balance sheet.
Preparing Blue Raider Adventure Park Financial Statements
The adjusted trial balance is used to organize financial information into formal statements.
For a basic accounting cycle problem, the required statements depend on the business structure and the instructor’s format. They commonly include an income statement and balance sheet, together with the relevant owner’s equity or retained earnings statement.
Income Statement
The income statement measures performance for a period.
At its simplest:
Revenue − Expenses = Net Income
If expenses exceed revenue, the business has a net loss.
OpenStax explains that the income statement reports the result of revenue and expense activity during the accounting period.
Statement of Equity
This statement explains changes in the owner’s or shareholders’ equity during the period.
The exact title and accounts depend on whether the entity is structured as a sole proprietorship, partnership, or corporation. Students should follow the entity type specified by their assignment instead of automatically using retained earnings or owner’s capital.
Balance Sheet
The balance sheet reports assets, liabilities, and equity at a particular date.
Its final totals must satisfy:
Assets = Liabilities + Equity
A balanced balance sheet is an important check, although, like a balanced trial balance, it does not independently prove that every underlying classification is correct.
Closing the Accounting Period
If the assigned Blue Raider Adventure Park packet requires closing entries, temporary accounts must be reset so a new accounting period can begin.
OpenStax explains that revenue and expense accounts are temporary accounts. Their balances are closed rather than carried forward indefinitely. Permanent accounts such as assets and liabilities continue into the following accounting period.
A post closing trial balance then checks that debits and credits remain equal and that only permanent accounts retain balances.
Whether this stage is included in a particular Blue Raider Adventure Park submission depends on the exact packet and instructions provided by the instructor.
A Better Way to Solve the Assignment
Trying to complete the entire packet from beginning to end without checkpoints makes errors difficult to find.
A more reliable approach is to build the answer in connected stages.
For every original transaction, first write the accounting equation effect. Then make the journal entry. Post that entry immediately to the ledger rather than waiting until all journal entries are complete.
Once the ledger is finished, prepare the unadjusted trial balance and stop if the columns do not agree. Do not attempt to hide a difference by changing a random account.
Next, treat every end of period adjustment as a separate accounting question:
What portion has now been earned, incurred, consumed, or expired?
Post those entries, calculate new ledger balances, and prepare the adjusted trial balance. Only then should the financial statements be prepared.
This sequence mirrors the accounting cycle taught in introductory financial accounting.
Common Blue Raider Adventure Park Accounting Mistakes
Confusing an Asset Purchase With an Expense
Buying equipment is normally different from paying an ordinary operating expense. Equipment can provide benefits beyond the current period, so its initial accounting treatment is not automatically the same as something such as utilities.
Recording Revenue Whenever Cash Arrives
Cash received and revenue earned are not always the same event.
If money is collected before a service is provided, the amount may initially represent unearned revenue rather than earned service revenue. The facts of the transaction determine the entry.
Ignoring Transactions on Account
No immediate cash movement does not mean no accounting transaction occurred.
Services can be earned before payment, and goods or services can be purchased before cash is paid.
Skipping Ledger Balances
A trial balance should be built from final ledger balances, not by copying random amounts directly from the transaction list.
Treating a Balanced Trial Balance as Proof of Accuracy
Debit and credit totals can agree while an incorrect account, duplicate transaction, omitted transaction, or other error remains. OpenStax explicitly warns that mathematical balance does not guarantee that the accounting records are correct.
Using Unverified Online Answer Keys
The publicly indexed Blue Raider Adventure Park material appears on third party homework platforms, and those platforms are not official MTSU sources. Course Hero itself states that it is not sponsored or endorsed by the universities whose course material appears on its platform.
That makes the original packet supplied through the course the safest source for transaction dates, dollar amounts, account names, and submission requirements.
Is Blue Raider Adventure Park a Real Business?
Based on the reliable public material located for this topic, Blue Raider Adventure Park is best understood as an accounting case or classroom business scenario, not as a verified operating adventure park.
The strongest exact match is attached to ACTG 2110 course material describing the adventure park scenario. Searches for the exact name do not produce an official business website or an MTSU page presenting it as an operating attraction. That absence should not be treated as proof that no similarly named entity has ever existed, but it makes the educational interpretation substantially better supported by the available evidence.
FAQ
What does blue raider adventure park accounting mean?
It most likely refers to an accounting cycle assignment associated online with MTSU’s ACTG 2110 Principles of Accounting I course. The scenario involves accounting for an adventure park business and applying financial accounting concepts across several stages of the accounting cycle.
Is Blue Raider Adventure Park part of MTSU?
The assignment is associated online with an MTSU accounting course, and “Blue Raiders” is MTSU’s official nickname. However, the available official university sources do not identify Blue Raider Adventure Park as an actual university operated attraction.
What course is the Blue Raider Adventure Park problem associated with?
Publicly indexed material associates it with ACTG 2110, Principles of Accounting I at Middle Tennessee State University. MTSU’s official catalog describes ACTG 2110 as a financial accounting course emphasizing the accounting cycle for service and merchandising organizations.
What accounting topics does the assignment cover?
The indexed description calls it an accounting cycle serial problem covering Chapters 2 through 4. Depending on the packet version, students may need to analyze transactions, prepare journal entries, post to ledger accounts, construct trial balances, process adjustments, and prepare financial statements.
Where can I find the exact Blue Raider Adventure Park answers?
Exact answers depend on the transactions, amounts, account titles, and instructions in the specific packet. Publicly indexed third party material should not be assumed to match the current assignment. The original course packet and instructor requirements are the appropriate sources for the underlying figures.
Why do my Blue Raider Adventure Park debits and credits not balance?
Common causes include posting an amount to only one side, putting a balance in the wrong debit or credit column, transposing digits, using the wrong ledger balance, or missing an entry. If the trial balance does not agree, trace the difference from the trial balance back through the ledger and then to the original journal entries.
