


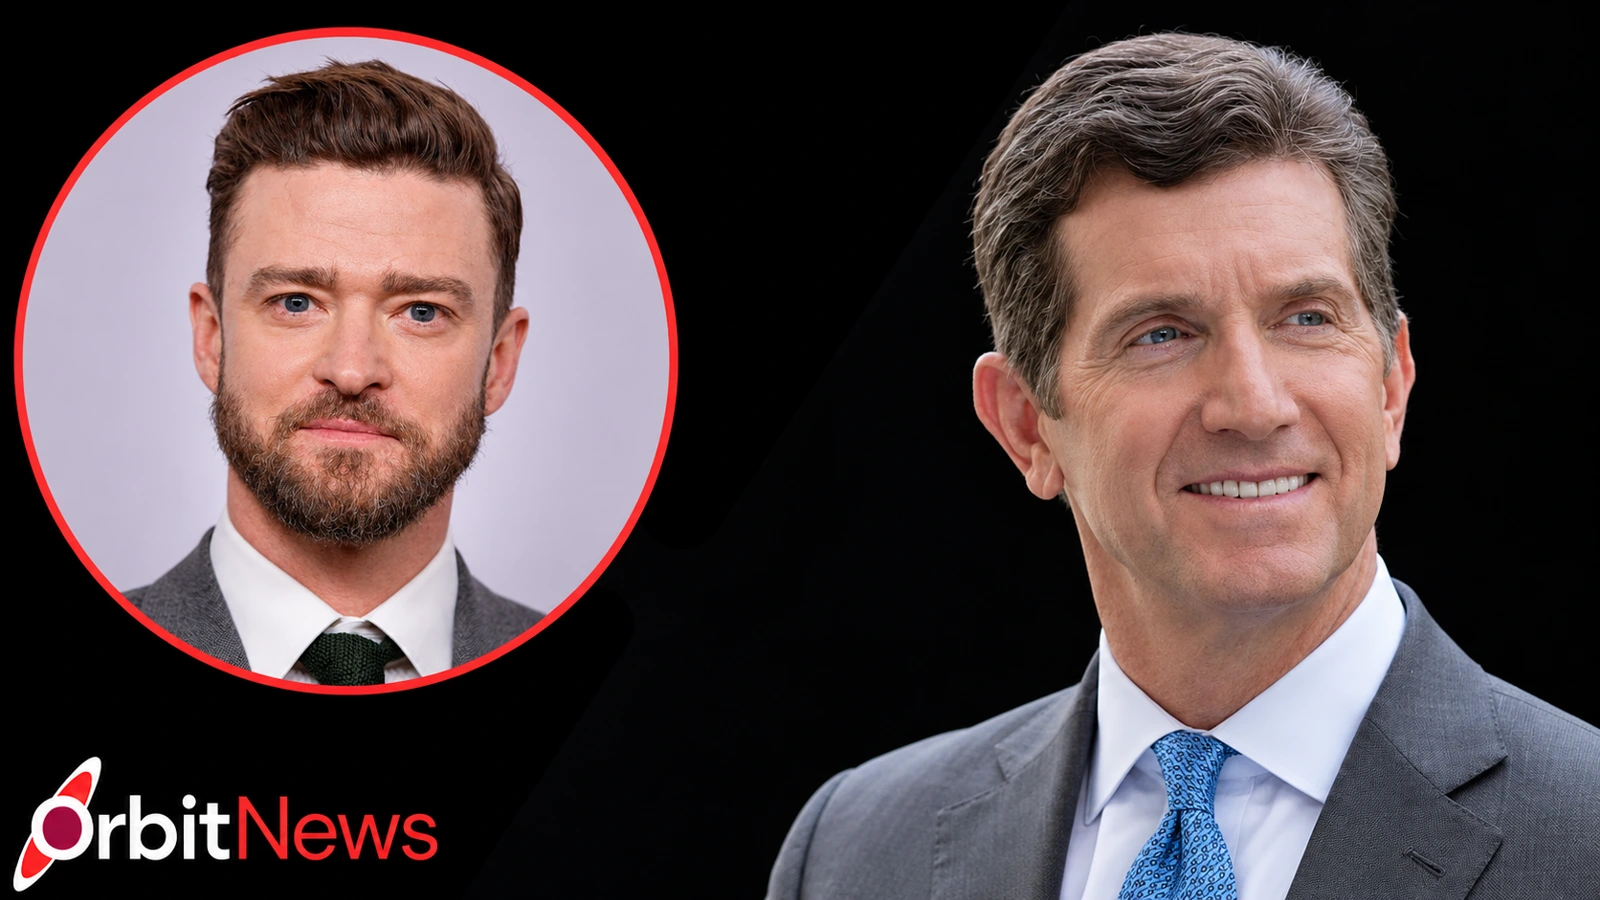
The Justin Timberlake and Alex Gorsky net worth comparison shows a larger published estimate for Timberlake, but not two equally complete personal valuations. Celebrity Net Worth lists Timberlake at approximately $250 million, checked on 13 November 2026. GuruFocus displays an at least $97 million stock-based indicator for Gorsky on that date, with a narrower scope.
The financial contrast concerns a recording artist’s mix of performance and intellectual-property interests beside a former executive’s publicly tracked securities. Timberlake’s 2022 song-catalogue transaction provides a documented business event. It should not be confused with ownership of every recording, an official disclosure of net proceeds or a reason to add the same asset value twice.

Justin Timberlake and Alex Gorsky Net Worth Comparison: What the Figures Mean
The Timberlake amount comes from Celebrity Net Worth’s profile, which identifies an update dated 12 October 2026. The Gorsky page supplies the partial securities indicator. Both amounts need their source labels rather than being presented as personal financial statements certified by the individuals.
| Individual | Published amount | Relevant limitation |
|---|---|---|
| Justin Timberlake | $250 million | Third-party celebrity-wealth estimate |
| Alex Gorsky | At least $97 million, 13 November 2026 | Limited stock-based calculation |
The difference between displayed amounts is not treated as a verified personal-wealth gap. A calculation cannot create the private asset and liability information missing from the sources. The useful conclusion is that Timberlake’s broad published estimate exceeds the cited Gorsky indicator, while the full personal comparison remains qualified.
The Hipgnosis Announcement Defines the Rights Sold
A Hipgnosis announcement dated 26 May 2022 confirms the acquisition of Timberlake’s interests in a catalogue of musical compositions. It specifies his copyright, ownership and financial interests associated with the writer’s and publisher’s share of public-performance income, as well as administration rights under the stated terms.
That scope matters more than an oversimplified claim that he sold all his music. Compositions and particular recordings are different rights. The announcement concerns defined songwriting-related interests, not a universal transfer of every possible asset connected with his entire performing career, past and future.
The release also identifies the acquisition as being made for Hipgnosis Songs Capital, a partnership involving funds managed by Blackstone. This names the business context of the transaction. It does not establish that the headline value of the buyer or its wider portfolio became Timberlake’s personal wealth.
Why the Sale Price Is Not Invented Here
The primary announcement cited does not publish a price. This article therefore does not attach an apparently official dollar amount to the agreement or construct Timberlake’s take-home proceeds from unsourced assumptions. Confirming that a rights transaction occurred is different from knowing every financial term.
Even a reliably reported gross transaction price would need further interpretation. The interests transferred, participants, costs and obligations affect the amount attributable to an individual. A headline can describe a business exchange without disclosing a complete personal after-tax result or the use of proceeds afterward.
The sale also exchanges an asset for another form of value. Counting the sold interest at its former valuation and then adding the full proceeds as independent continuing wealth can duplicate the same economic resources. A current estimate may already consider the relevant transaction, so an extra homemade addition is not justified.
Recordings, Songs and Performances Create Different Payment Paths
A listener may think of a familiar track as a single product, but the underlying composition and recorded performance can involve separate owners and agreements. Songwriting, recording and performance participation do not necessarily belong to the same person in identical proportions. Credits do not replace the contracts governing those rights.
That distinction is particularly important for a performer whose career includes solo work and group work. A public catalogue association does not establish an equal share of every receipt or complete personal ownership of every release. The relevant right must be identified before a financial claim can be made.
The article therefore avoids multiplying total plays or sales by one universal royalty rate. A stream count can show audience activity while leaving the actual allocation of money unresolved. It is not enough to reconstruct an individual’s retained wealth or the precise value of a rights interest.
Touring Receipts Are Not the Artist’s Net Income
A tour can be a substantial commercial operation with venues, production, staffing, travel and other commitments. Gross ticket receipts describe money collected around the event before the relevant costs and contractual allocations. They cannot simply be copied into the headline performer’s personal-wealth total.
The timing is different as well. Announced dates concern future work, while an estimate attempts to describe an existing financial position. A schedule is not proof that every possible payment has already been earned or retained. The actual outcome depends on delivery and the agreement’s terms.
For Timberlake, the comparison does not forecast touring profit or apply a guessed margin to a reported gross. His performance career supplies context for potential income, while the attributed personal estimate supplies the financial snapshot. Those roles should remain distinct rather than being combined into a speculative private ledger.
Gorsky’s Career Requires a Current Description
Apple identifies Gorsky as Johnson & Johnson’s retired CEO and executive chairman. A financial tracker retaining an older CEO label is not the best authority for his current operating role. The distinction prevents a dated description from becoming a false present-tense claim in a new article.
His stock indicator also should not be treated as the total value of Johnson & Johnson or any other company associated with his career. A corporation has separate assets, shareholders and obligations. An executive’s personal interest depends on attributable holdings and other rights, not ownership of the entire business by virtue of a title.
This creates a useful parallel with entertainment. A performer does not personally receive all ticket sales, just as a corporate leader does not personally receive all company revenue. Both financial stories require attention to actual economic interests rather than the biggest number appearing beside a famous name.
Professional Honours Are Evidence of a Career, Not a Payment Schedule
The May 2022 Hipgnosis release described Timberlake as a ten-time Grammy winner at that point. That historical statement supports the professional context of the transaction without claiming to provide an updated November 2026 awards count. Recognition and financial rights remain different measures.
A long record of success can help explain why a catalogue attracts commercial interest, but it does not establish a fixed price per award or per familiar song. The actual rights and transaction terms still determine the economic interest. This article therefore keeps career achievement beside the financial analysis rather than converting it into an invented additional asset value.
Frequently Asked Questions
Who has the larger published amount?
Timberlake’s $250 million celebrity estimate is larger than Gorsky’s cited $97 million stock-based indicator. The comparison is qualified because the measures are not equally comprehensive. It does not establish the exact difference between their complete personal assets after all liabilities.
Did Timberlake sell every recording he ever made?
The cited Hipgnosis release concerns specified interests in musical compositions and related income and administration rights. It should not be broadened into a claim about every recording or future work. The wording of the primary announcement defines what can reliably be said about the transaction.
Is the catalogue deal’s price officially disclosed in that release?
The announcement used here does not publish a price. This article does not invent one or describe a separately reported amount as an official term. A confirmed transaction and a verified personal take-home figure are different levels of financial evidence.
Can concert grosses be added directly to Timberlake’s net worth?
No. Gross event receipts precede operating costs and contractual allocations, and past income may already be reflected in an estimate of accumulated assets. Adding headline grosses to a current estimate could both overstate personal income and count the same economic activity more than once.
For another rights-focused comparison, OrbitNews’s Katy Perry article discusses the scope of a documented music partnership. Its Taylor Swift analysis separates catalogue ownership, live performance and estimated personal wealth.
