


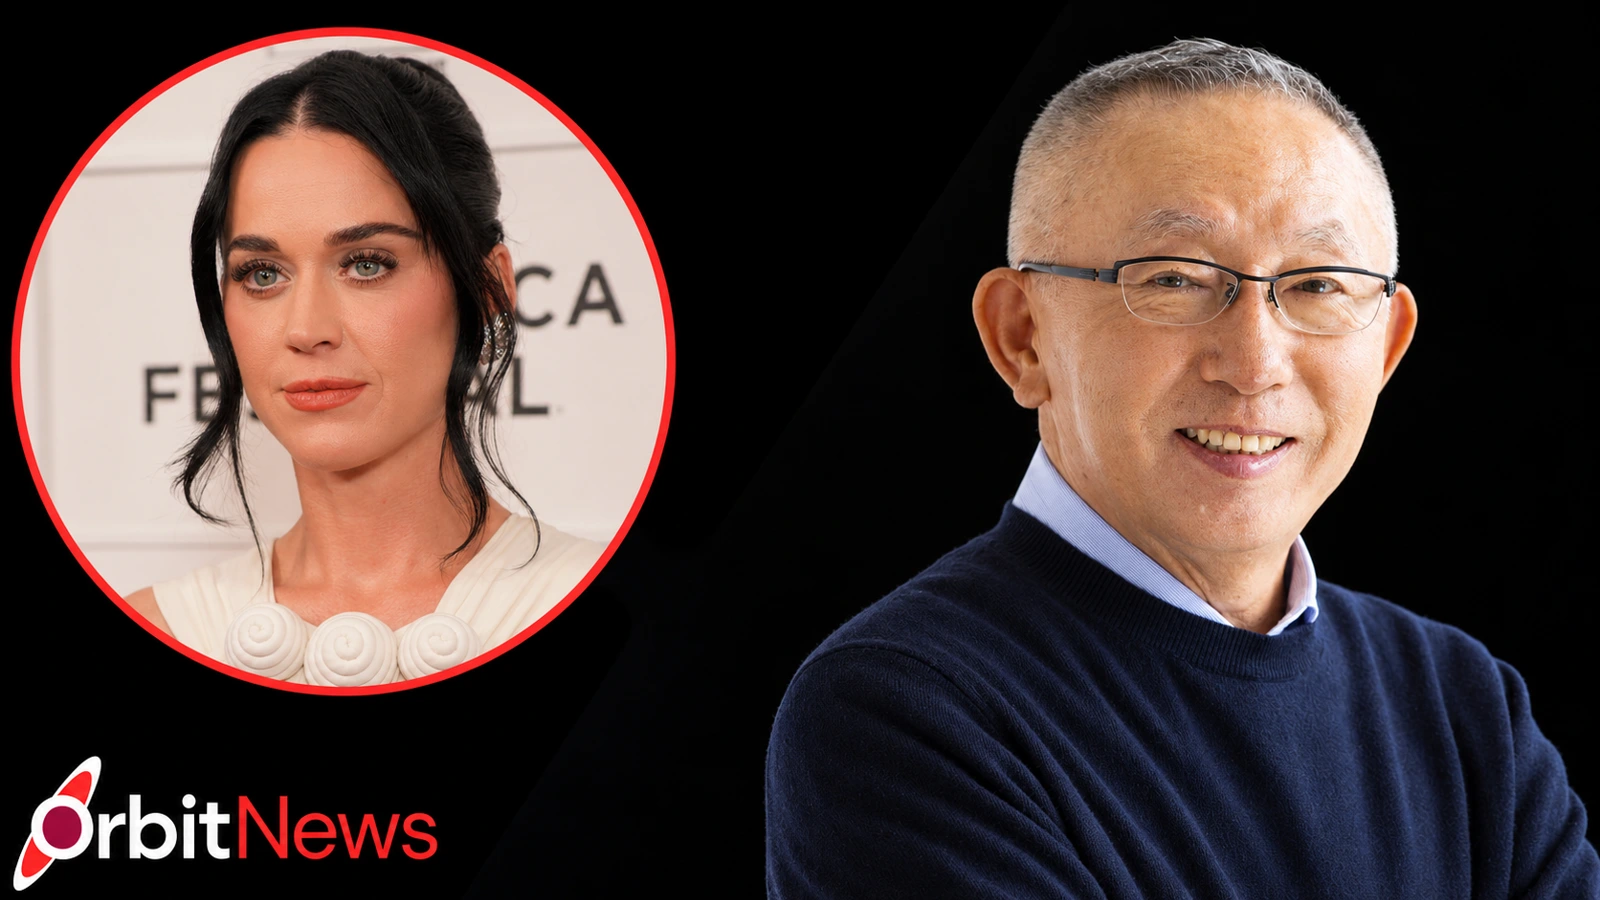
The Katy Perry and Tadashi Yanai net worth comparison places a major entertainment career beside a much larger founder-family estimate. Celebrity Net Worth lists Perry at approximately $400 million, checked on 12 November 2026. Forbes estimates Tadashi Yanai & family at $68.6 billion on 12 November 2026. The family label must remain attached; the whole amount is not presented here as Yanai’s separately verified individual fortune.
Perry’s career raises questions about recording rights, performances and transactions involving music. Yanai’s financial context concerns a large retail business and attributable ownership. The comparison is useful when it explains those different assets rather than treating every customer receipt, catalogue headline or company sale as direct personal income.

Katy Perry and Tadashi Yanai Net Worth Comparison: The Evidence
The $400 million amount comes from Celebrity Net Worth’s Perry profile. The $68.6 billion amount comes from Forbes’s Tadashi Yanai & family profile. They are attributed estimates with different scopes, rather than complete audited personal accounts supplied by the individuals.
| Subject | Published estimate | Scope distinction |
|---|---|---|
| Katy Perry | $400 million | Individual celebrity estimate |
| Tadashi Yanai & family | $68.6 billion | Family-labelled Forbes estimate |
The broad scale difference is clear without an exact individual ratio. The article does not divide the family estimate among relatives or assume that all of it belongs to Yanai alone. A compatible separately attributed personal valuation would be needed before claiming a precise individual-to-individual wealth relationship.
A Documented Music Partnership Provides Better Context Than Rumour
A Carlyle announcement dated 18 September 2023 describes Litmus Music’s creative partnership with Perry. It says the arrangement covers her five Capitol studio albums released between 2008 and 2020. That is primary evidence of a music-rights business relationship, with a defined catalogue scope.
The announcement is not a complete personal financial statement. It does not establish every net payment, obligation or later use of proceeds relevant to Perry’s wealth. This article therefore does not attach an invented take-home amount to the partnership or assume that all interests across every future release are covered by the same arrangement.
The source is valuable because it identifies what was announced and when. It provides a firmer basis for discussing rights than an unsourced claim that an artist sold everything. Preserving the catalogue period and the announcement’s wording prevents a specific transaction context from becoming an exaggerated statement about all creative ownership.
Rights Transactions Do Not Automatically Create New Wealth Dollar for Dollar
Selling or transferring an interest can exchange one form of asset for another. Before the transaction, the owner has a right; afterward, they may have proceeds or another economic position. Counting the old right and the full proceeds as independent continuing assets could duplicate the same value.
A headline transaction amount also differs from net proceeds retained by an individual. The interests exchanged, participants, costs and obligations matter. Without a complete agreement and financial record, the public cannot assume that every dollar reported around a transaction became unrestricted personal cash.
This is why the article does not add a catalogue-deal headline to Perry’s current estimate. The estimating publication may already consider related assets or proceeds, and a homemade addition could count them twice. The documented partnership supplies context, while the published personal estimate supplies the dated financial reference point.
Composition, Recording and Performance Are Separate Questions
The underlying song and a particular recording are different rights. An artist can participate in one or more interests under agreements that vary across releases. The public’s familiarity with a singer’s voice does not establish complete ownership of all composition and recording rights associated with every song.
Live performance adds a separate operating activity. Ticket receipts support an event with production, venues, staff, travel and other commitments. The gross amount collected from audiences is not the same as the performer’s personal profit or the value of an existing catalogue interest.
For Perry, the comparison therefore recognises a broad entertainment career without manufacturing a detailed private asset schedule. Recording activity, live work and other professional roles can all be relevant, but their actual financial outcomes depend on rights and terms that are not fully visible in a public biography.
Yanai’s Retail Interest Operates on Another Scale
Fast Retailing’s official profile identifies Yanai as chairman, president and chief executive officer. The corporate role establishes professional context. The personal-wealth question depends on the economic interests attributable under the relevant ownership structure, rather than all resources controlled operationally by the company.
A valuable business interest can change in market value without creating a corresponding cash payment. Likewise, company sales belong first to the business and precede relevant costs and allocations. Assigning every store receipt to the founder would be as misleading as assigning every music sale directly to the singer.
The family-labelled Forbes amount creates a further distinction from Perry’s individual estimate. This article preserves that scope instead of silently changing it. The broad difference in published scale remains useful, while the evidence does not support allocating the entire family total to one separately valued individual.
What These Two Models Have in Common
Both music rights and business ownership can have value beyond the next payment for current work. Their value can reflect expectations about future economic benefits. That does not make all projected future receipts cash already received, nor does it guarantee a sale at a displayed or estimated valuation.
Both also require care about the owner. A singer, a rights business, a retailer and a founder-family group are different financial subjects. A familiar name can connect them publicly without merging their assets and obligations. A professional comparison identifies the subject before using the number.
The article consequently avoids a false salary contest. Annual compensation is only one possible flow within a wider financial history. Net worth concerns accumulated assets after liabilities at a date, while the cited family estimate has an additional scope that prevents a precise individual ratio against Perry.
A Catalogue Period Defines What the Announcement Covers
An announcement identifying a particular period should not be extended automatically to later work. Future recordings and other rights can have different arrangements. The public needs the actual scope before assuming that a transaction covers every creative asset an artist has produced or may produce.
For Perry, the 2008-to-2020 album period is retained because it is part of the primary announcement. The comparison does not replace that defined scope with a claim that all future music belongs to the same partnership. Clear boundaries make the rights discussion useful without turning a specific business event into a fictional complete transfer of the artist’s career.
Frequently Asked Questions About Perry and Yanai
Which published amount is larger?
The Forbes Tadashi Yanai & family estimate is much larger, at approximately $68.6 billion compared with Perry’s $400 million Celebrity Net Worth estimate. The figures were checked for 12 November 2026. The family label remains essential whenever the comparison is repeated.
Does the Litmus announcement cover every future Perry album?
The cited announcement identifies five Capitol studio albums released between 2008 and 2020. It should not be expanded into a claim about every future release or every possible creative right. A specific announced catalogue scope needs to be preserved rather than replaced with a broader unsupported statement.
Is a catalogue transaction all new personal profit?
Not necessarily. A transaction can exchange an existing asset for proceeds, and net retained amounts depend on the interests and obligations involved. Adding a headline price to an existing estimate could duplicate value. The announcement alone does not supply a complete personal take-home calculation.
Is Yanai’s family figure his separately verified personal wealth?
The cited Forbes profile explicitly includes family. This article does not allocate the total or assign all of it to Yanai individually. A clean personal ratio would require compatible individual valuations, rather than removing a source label to make the arithmetic look simpler.
OrbitNews’s Taylor Swift comparison explores another music-rights context. Its Tina Fey article considers writing and production alongside the same family-labelled retail estimate.
